Flood Insurance vs Homeowners Insurance in New Orleans, LA
This page is specifically about distinguishing flood coverage from homeowners coverage when water enters a property. This local version applies the intent to New Orleans without pretending that the city name changes the underlying physics of water damage.
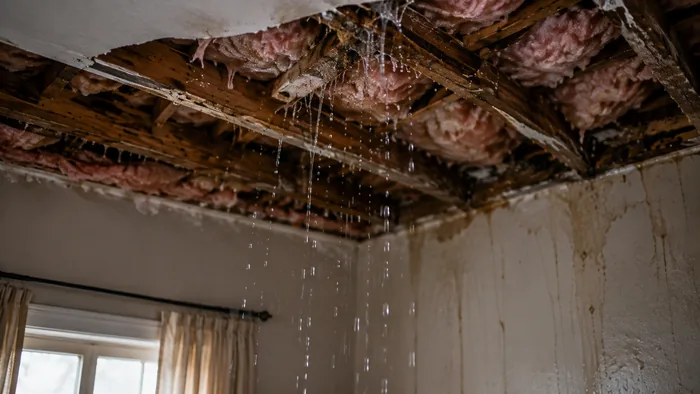
How this intent differs from general water damage restoration
This page is specifically about distinguishing flood coverage from homeowners coverage when water enters a property.
That distinction matters because a homeowner searching for flood insurance vs homeowners insurance is usually comparing a narrower decision than someone researching restoration generally. The page therefore emphasizes the work, risks and estimate questions that belong to this intent.
Why the path of water matters
Rising exterior water is generally treated differently from a burst pipe, appliance leak or some roof intrusions. The cause of loss should be documented before assuming which policy applies.
Why restoration scope still comes first
Even when coverage is uncertain, the building still needs a physical scope. Extraction, cleaning, drying and repair should be documented independently from the coverage decision.
What homeowners should avoid assuming
Do not assume that all 'water damage' is handled under the same policy language. Flood insurance is commonly a separate product with a separate claim process.
How documentation supports both tracks
Photos, source information, water lines, contractor scope and receipts help explain the physical loss while insurance representatives determine the applicable coverage.
How to compare this service in New Orleans
| Question | What to compare |
|---|---|
| Problem definition | Is the contractor solving the same intent described on this page? |
| Affected area | Are the same rooms, surfaces and hidden assemblies included? |
| Materials | Are both providers making the same dry-vs-remove assumptions? |
| Equipment or labor | Do quantities and days reflect the same technical plan? |
| Cleaning or contamination | Are special procedures included when the water source requires them? |
| Reconstruction | Is final repair included, excluded or quoted separately? |
How adjacent rooms can become involved
Water can move through continuous flooring, shared walls and lower levels. The discovery room is not always the full damage boundary.
What a useful monitoring plan looks like
The contractor should be able to explain when the property will be rechecked, what readings will be taken and what conditions justify removing equipment.
Why access drives labor
Cabinets, tight crawlspaces, glued flooring and finished assemblies can make inspection and drying more labor-intensive than open areas.
What completion should mean
Ask whether the provider's job ends at dry structure, debris removal, cleaned surfaces or completed reconstruction. Different definitions create different prices.
Why material type matters
Drywall, wood, laminate, carpet, insulation and cabinets absorb and release moisture differently. Treatment should follow material behavior, not just room size.
Why this page does not use a generic city template
The search intent matters more than the city label. A sewage-cleanup page should discuss contamination and material handling; a flood-cleanup page should discuss exterior water, sediment and flood coverage; an extraction page should discuss standing-water removal and the transition to drying. Those are different decisions and this rewrite treats them as such.
How this intent plays out in New Orleans
New Orleans sits within a Louisiana context shaped by tropical systems, exterior flooding, high humidity, drainage stress and wind-driven rain. That context can change access, drying conditions and insurance questions, but the service intent still determines what this page should answer.
What to keep when flood coverage may apply
Preserve photos, inventories, receipts, repair estimates and source information so the physical loss can be evaluated under the appropriate claim process.
Why the deductible question comes later
First determine which coverage applies. Deductibles and settlement terms only make sense once the correct policy path is identified.
How one storm can create multiple causes
A storm can produce roof intrusion, broken windows and exterior flooding at the same property. Those sources may need separate documentation and insurance analysis.
Why homeowners wording should not be assumed to include flood
Flood coverage is commonly separate. The safest approach is to review the actual policy rather than treating 'water damage' as one coverage category.
How to compare the two insurance paths
Start with the physical source of water, then identify which policy or program may apply. The same damaged wall can belong to different claim paths depending on how the water arrived.
How to compare line items instead of totals
Put both estimates side by side and compare quantities, equipment, demolition, cleaning, disposal and reconstruction. A total alone hides the reason for disagreement.
How elapsed time changes scope
Longer exposure can allow water to move deeper into porous materials and hidden assemblies, changing what can be dried in place.
Why a local page should avoid fake specificity
Invented city prices and fabricated provider lists create the appearance of local expertise without evidence. Decision-specific guidance is more useful.
What to ask when a material is being removed
The provider should be able to explain whether removal is driven by contamination, damage, access or inability to dry.
Page-specific decision notes for New Orleans
A practical New Orleans scope for cause-of-loss classification and the distinction between flood and homeowners coverage should not ignore tropical systems, especially when water may have reached drywall. If the affected area is under continuous flooring, the provider should confirm access conditions and verify the moisture boundary before treating the project as complete. The useful question is whether selective removal is necessary, not whether the page can produce a decorative local average.
In New Orleans, a cause-of-loss classification and the distinction between flood and homeowners coverage decision can become more complicated when stormwater entry intersects with moisture in laminate. If the affected area is below a finished ceiling, the provider should verify access conditions and trace the moisture boundary before a price comparison is meaningful. That matters because the homeowner ultimately has to decide whether contents must be moved or inventoried.
In New Orleans, a cause-of-loss classification and the distinction between flood and homeowners coverage decision can become more complicated when stormwater entry intersects with moisture in laminate. Because the material may be inside wall cavities, it is reasonable to ask how the contractor will separate hidden moisture and compare the result before the claim scope is challenged. The useful question is whether the claim file needs a revised scope, not whether the page can produce a decorative local average.
A practical New Orleans scope for cause-of-loss classification and the distinction between flood and homeowners coverage should not ignore stormwater entry, especially when water may have reached laminate. When the problem sits behind baseboards, the estimate should explain how the team will separate the assembly and trace any change in scope before reconstruction is authorized. This is the point where a local guide should help with how many equipment days are supportable rather than repeat national copy.
One reason two New Orleans estimates can diverge is that one provider may account for high humidity while the other treats subfloor as a simple surface issue. Because the material may be beneath appliance platforms, it is reasonable to ask how the contractor will verify hidden moisture and compare the result before demolition expands. The useful question is whether selective removal is necessary, not whether the page can produce a decorative local average.
For a New Orleans property, cause-of-loss classification and the distinction between flood and homeowners coverage is easier to evaluate when the contractor first accounts for drainage stress and then inspects ceiling assemblies. When the problem sits inside wall cavities, the estimate should explain how the team will confirm the assembly and document any change in scope before the homeowner signs a broader work authorization. This is the point where a local guide should help with how many equipment days are supportable rather than repeat national copy.
A practical New Orleans scope for cause-of-loss classification and the distinction between flood and homeowners coverage should not ignore high humidity, especially when water may have reached subfloor. Because the material may be behind baseboards, it is reasonable to ask how the contractor will separate hidden moisture and verify the result before equipment is removed. That matters because the homeowner ultimately has to decide whether cleaning must precede drying.
A practical New Orleans scope for cause-of-loss classification and the distinction between flood and homeowners coverage should not ignore high humidity, especially when water may have reached carpet pad. Because the material may be below a finished ceiling, it is reasonable to ask how the contractor will separate hidden moisture and record the result before the homeowner signs a broader work authorization. This is the point where a local guide should help with whether reconstruction belongs in the same estimate rather than repeat national copy.
For a New Orleans property, cause-of-loss classification and the distinction between flood and homeowners coverage is easier to evaluate when the contractor first accounts for stormwater entry and then inspects laminate. If the affected area is behind built-in cabinets, the provider should justify access conditions and compare the moisture boundary before treating the project as complete. This is the point where a local guide should help with whether reconstruction belongs in the same estimate rather than repeat national copy.
In New Orleans, a cause-of-loss classification and the distinction between flood and homeowners coverage decision can become more complicated when stormwater entry intersects with moisture in drywall. Because the material may be beneath appliance platforms, it is reasonable to ask how the contractor will document hidden moisture and justify the result before the claim scope is challenged. The useful question is whether drying in place is reasonable, not whether the page can produce a decorative local average.
Estimate the physical scope before comparing providers
Use Water Damage Calculator to organize rooms, materials and loss type before you compare quotes.
Calculate Water Damage →Frequently asked questions
Is rising exterior water usually handled like a plumbing leak?
No. It is generally a separate insurance question.
Does homeowners insurance automatically include flood coverage?
Usually not. Flood coverage is commonly separate.
Can restoration start before coverage is fully resolved?
Emergency mitigation may still be necessary, but work should be documented carefully.
Should I document the source of water?
Yes. How the water entered can be central to the insurance analysis.
Why should I ask where the scope ends?
One provider may stop after mitigation while another includes full repairs.
Do all wet materials need to be removed?
No. The decision depends on material, contamination, deformation, access and drying potential.
What is the role of the calculator?
It helps organize a planning estimate before you compare contractor proposals.
How do I know if a contractor is quoting the same scope as another?
Compare rooms, quantities, materials, equipment, demolition, cleaning, reconstruction and exclusions.
What should I do if the source is still active?
Control or isolate the source if it can be done safely before relying on drying alone.
Can odor disappear before the problem is solved?
Yes. Odor control does not prove that contamination or hidden moisture is resolved.
Why are moisture readings important?
They help define the affected area and show whether drying is progressing.
Can I hire separate mitigation and reconstruction companies?
Yes. Those phases can be separated.