Water Damage Restoration in Fresno, CA
Fresno property owners can face water losses shaped by long dry periods interrupted by heavy rain and a wide range of urban building types. Building access also matters because single-family homes, apartments, condominiums and multifamily buildings with shared systems can hide moisture in very different ways.
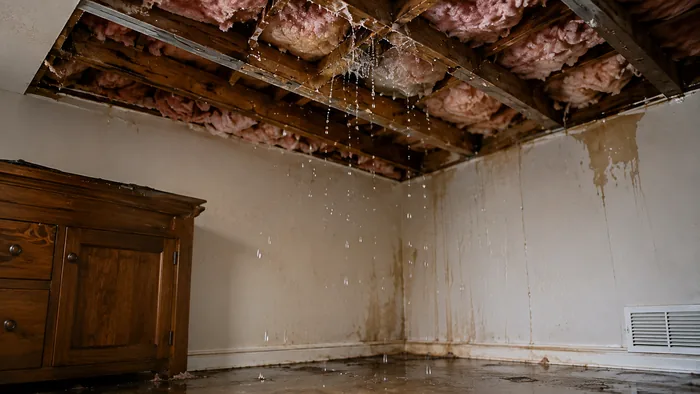
Local restoration context in Fresno
California conditions can include long dry periods interrupted by heavy rain and a wide range of urban building types. Property types such as single-family homes, apartments, condominiums and multifamily buildings with shared systems can affect how easily a contractor can inspect floors, walls, ceilings and concealed cavities.
Common loss categories worth separating include plumbing leaks, appliance failures, roof leaks, slow hidden leaks and water migration between units. Those are planning categories, not fabricated city-level frequency statistics.
Plan the transition to reconstruction
Drying can be technically complete while the home is still missing flooring, drywall, cabinets or trim. Ask who owns the handoff and what documentation accompanies it.
Think in layers
Flooring may cover underlayment and subfloor; walls may contain insulation and framing; cabinets can trap moisture behind toe kicks. A local estimate should make clear which layers were actually evaluated.
Ask what is excluded
A low estimate may omit content handling, demolition, cleaning, reconstruction or source repair. Exclusions often explain more of the price gap than hourly rates or equipment charges.
Ask who repairs the source
The restoration company may not repair the failed pipe, roof, appliance or HVAC component. Clarifying responsibility avoids starting drying while the original source remains unresolved.
Review drying days carefully
The number of equipment days should have a reason behind it. More days do not automatically mean better work, and fewer days do not automatically mean efficiency. Progress should be supported by measurements.
Keep insurance separate from technical scope
Coverage does not determine what the building physically needs. First establish the restoration scope, then compare that scope with policy terms and insurer decisions.
Understand the role of outside humidity
Opening windows is not automatically helpful. In humid conditions, outside air can slow drying. The drying plan should consider indoor and outdoor moisture conditions rather than rely on intuition.
Think about occupied-space constraints
Pets, children, tenants, narrow hallways and limited electrical circuits can change how equipment is placed and how work is sequenced. Occupancy can affect logistics even when the wet area is modest.
Review authorizations before signing
Emergency-service documents can authorize immediate work, direct billing or other terms. Reading them before signing helps avoid surprises once mitigation has started.
Document changes in scope
If wet insulation, subfloor or hidden wall damage appears after selective demolition, the scope may legitimately change. That change should be tied to a specific condition, photograph or measurement.
Three loss scenarios to think through in Fresno
Roof leaks
When a loss begins with roof leaks, the first task is to confirm the source and map how far moisture moved. The repair decision then depends on contamination, material type, access and elapsed time. The same source can create a minor job in one property and a much larger project in another.
Slow hidden leaks
When a loss begins with slow hidden leaks, the first task is to confirm the source and map how far moisture moved. The repair decision then depends on contamination, material type, access and elapsed time. The same source can create a minor job in one property and a much larger project in another.
Water migration between units
When a loss begins with water migration between units, the first task is to confirm the source and map how far moisture moved. The repair decision then depends on contamination, material type, access and elapsed time. The same source can create a minor job in one property and a much larger project in another.
How to compare two Fresno restoration estimates
| Item | What to compare | Why it matters |
|---|---|---|
| Rooms and surfaces | Exact areas included | Different boundaries create different totals. |
| Materials | Dry in place vs remove | Material decisions change mitigation and rebuild scope. |
| Equipment | Type, count and estimated days | Drying plans should be comparable. |
| Cleaning | Standard cleaning vs contaminated-loss procedures | Source and contamination change the work. |
| Reconstruction | Included or excluded | A mitigation-only quote is not a full repair quote. |
| Documentation | Photos, moisture logs and change orders | Written records make scope changes easier to verify. |
What this page deliberately does not invent
There is no reliable reason to publish a made-up “average Fresno price” or a fictional list of local providers just to make a page look more specific. Where no dependable city-level data exists, this guide focuses on the real decision variables that change scope and cost.
Estimate the physical scope before comparing quotes
Use Water Damage Calculator to organize rooms, materials and loss type before you compare contractor proposals.
Calculate Water Damage →Additional questions before you hire
How to separate source repair from restoration
The failed pipe, roof opening, appliance line or drainage problem may need a different trade. Confirm whether source repair is included, excluded or already completed so that the restoration estimate is not mistaken for a complete solution.
How to review a drying log
A drying log should show that the contractor is tracking conditions over time rather than simply leaving equipment in place. Look for dates, affected materials, moisture readings, atmospheric conditions and notes explaining changes to equipment or scope.
Frequently asked questions
How should I compare equipment charges?
Compare the number and type of devices, expected duration and the monitoring plan, not only a daily rate.
Can I hire one company for mitigation and another for reconstruction?
Yes. Those phases can be separated if that better fits the project.
Can odors remain after drying?
Yes. Odor can come from contamination, contents or materials that still need cleaning or removal.
Why is monitoring important?
It shows whether moisture levels are actually improving and helps determine when equipment can be removed.
Can a wall be wet even if it looks dry?
Yes. Moisture can remain inside drywall, insulation or framing before there is an obvious surface sign.
What is a change order?
A written change to the original scope or price, usually because new conditions were discovered or work changed.
Can the calculator replace a contractor estimate?
No. It is a planning tool. A binding estimate requires a local inspection.
Should the contractor explain why materials are removed?
Yes. The reason should relate to contamination, damage, access or inability to dry the material effectively.
Is exterior flooding the same as a plumbing leak for insurance?
Usually not. Flood losses are generally treated as a separate insurance question from many interior water losses.
Does the restoration company repair the leak source?
Not necessarily. A plumber, roofer, HVAC technician or another trade may be needed.
Why should I ask where the scope ends?
Because one estimate may stop at dry structure while another includes the final repairs.
Does homeowners insurance automatically cover water damage?
No. Coverage depends on the cause of loss, policy language, deductible and exclusions.